Business Is Growing, but Who Pays for That Growth?
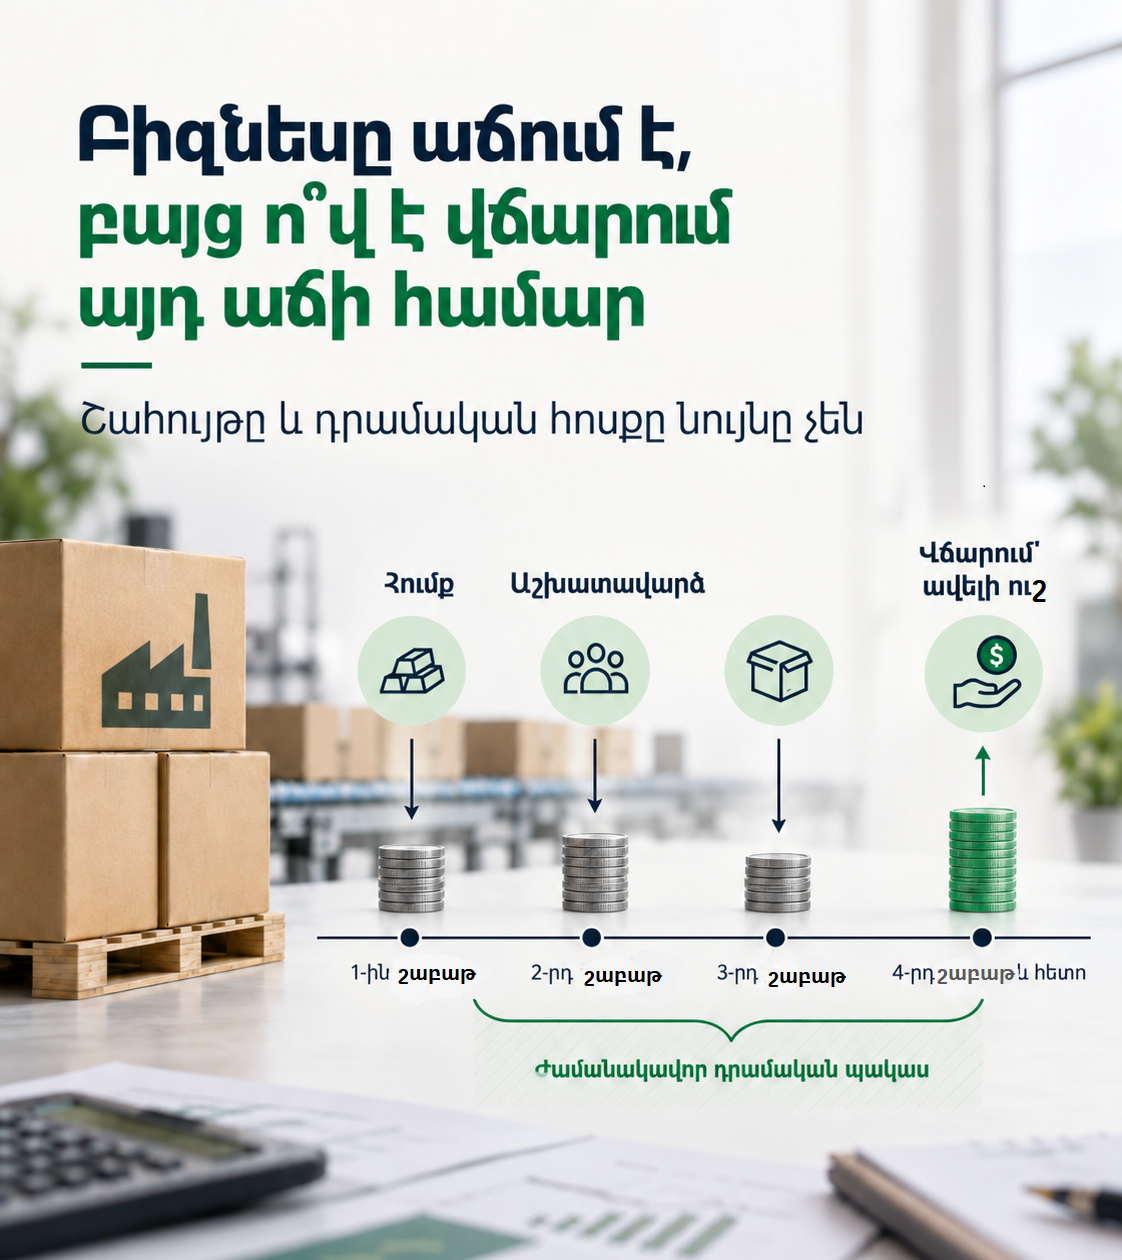
On Monday morning, the director of a manufacturing company received a call from its largest customer. The customer was ready to order almost three times as much as usual. The contract promised substantial revenue, work for the team, and impressive growth in the year-end figures. The director agreed on a price and, by evening, was already telling colleagues that the company was entering a new phase. There was just one question nobody had asked: who would pay for the order until the customer settled the bill?
The goods had to be produced within six weeks. The supplier of raw materials required a 50 percent advance payment and the other half upon delivery. Expanding production would mean overtime, additional packaging, and transport. Under the contract, however, the customer would pay sixty days after receiving the goods. In other words, the company would have to get through nearly four months between its first expense and the final payment. Regular payroll and the costs of other orders would not disappear in the meantime.
At first, the difficulty was hard to see. There was money in the bank, the new contract seemed profitable, and the director calculated that the company had enough. Two weeks later, the supplier's payment fell due. A week after that came payday. Then it turned out that the carrier's rate was higher than the initial estimate. The company had not lost its profit, but it was beginning to lose the freedom to make payments when they were due.
This situation is deceptive because it hardly sounds like bad news. Sales are rising, customers are happy, and orders are multiplying. Owners usually worry when sales decline. When they grow quickly, it can seem that any cash problem will solve itself. In reality, every new order may require cash first and return it only later. The larger the order, the greater that temporary need can be.
Profit and cash do not arrive at the same time. If a company has sold goods for one million drams, that does not mean the million is already in its bank account. The goods may be ready, the invoice issued, and the revenue recorded, while payment is due two months later. Materials, wages, and transport may need to be paid for today. Accounting helps show the result of a transaction, but running the business also requires a calendar of the payments needed to reach that result.
The director asked the accountant to map out payments over the coming weeks. A simple table placed expected receipts alongside existing commitments and the costs of the new order. The figures showed that, in week six, the account balance might be insufficient even if the customer paid exactly on the date specified in the contract. A delay of just a few days would widen the gap. The problem was not the order's overall profitability. It was the period during which the company would finance the customer's order with its own money.
The calculation did not make the decision for the director, but it changed the negotiations. The company proposed an advance payment and deliveries in smaller batches. It discussed postponing the second payment to its supplier. It also adjusted the delivery schedule for another order so several large payments would not fall in the same week. Each change was small, but together they reduced the financial pressure during the most difficult weeks.
This is why it is not enough to ask, “How much will we earn?” Before signing a large contract, it helps to know how much cash must be spent before the first receipt, when payments fall due, what happens if a payment is late, and whether enough will remain to keep day-to-day operations running. The same questions matter when a company hires staff, builds inventory, or starts several projects at once.
Sometimes the director tries to solve the problem with a credit line. It can be useful if the size and duration of the shortfall are clear and the financing cost is included in the order calculation. But borrowing has a cost of its own. If interest and possible delays are left out when setting the price, a deal that looks attractive on paper may deliver a much smaller return. Bank financing also cannot guarantee that the customer will pay on time or that favorable terms can be agreed with suppliers.
For the same reason, looking only at the month-end bank balance is not enough. There may be plenty of cash at the end of the month, yet a payment problem in the middle of it. It is more useful to look at expected receipts and outgoings week by week and update the forecast regularly. The sales manager can flag a likely change to the contract, the purchasing manager can share new supplier terms, and the accountant can identify existing liabilities and tax payments. Once that information is brought together, the full demand on cash becomes visible.
This does not require a complicated financial model. Four columns are enough to start: payment date, expected receipt, required expense, and forecast balance. But each figure should carry an appropriate level of confidence. Treating a payment due under a signed contract and a customer's verbal promise as equally certain can create a misleading picture. It also helps to prepare a cautious scenario: assume that one receipt is delayed and one cost rises slightly. If the company can still meet its core obligations, the decision rests on firmer ground.
Another point deserves attention: the moment a sales plan begins to dictate purchasing volumes. Buying a large batch of raw materials to secure a discount can be tempting. But unused stock is cash tied up in inventory. Even a good discount will not help if it leaves the company unable to pay wages or complete another order on time. Sometimes buying in smaller stages at a higher unit price is the safer and ultimately more profitable choice.
These conversations should take place before promises are made to the customer. If the financial calculation is done only after the contract is signed, there is less room to negotiate an advance or different payment terms. When the people responsible for accounting and sales share information from the outset, the director can choose terms that work for both the customer and the company.
The company in this story accepted and fulfilled the order. The customer paid, the team produced the goods on time, and the contract generated a profit. But large sales alone did not account for that success. The company saw in advance which weeks would require cash and changed the terms while it still could. Without those steps, the same profitable order might have disrupted smaller but essential everyday payments.
Growth is usually presented on a sales chart. That chart is encouraging, but it does not tell the whole story. A growing business also needs an answer to a simple question: how will it operate until the money from new sales comes in? When the owner, the sales team, and the accountant answer that question together, a new order becomes an opportunity the company can manage, rather than an unexpected test of its cash reserves.