How Much Profit Do You Really Lose When You Offer a 20% Discount?
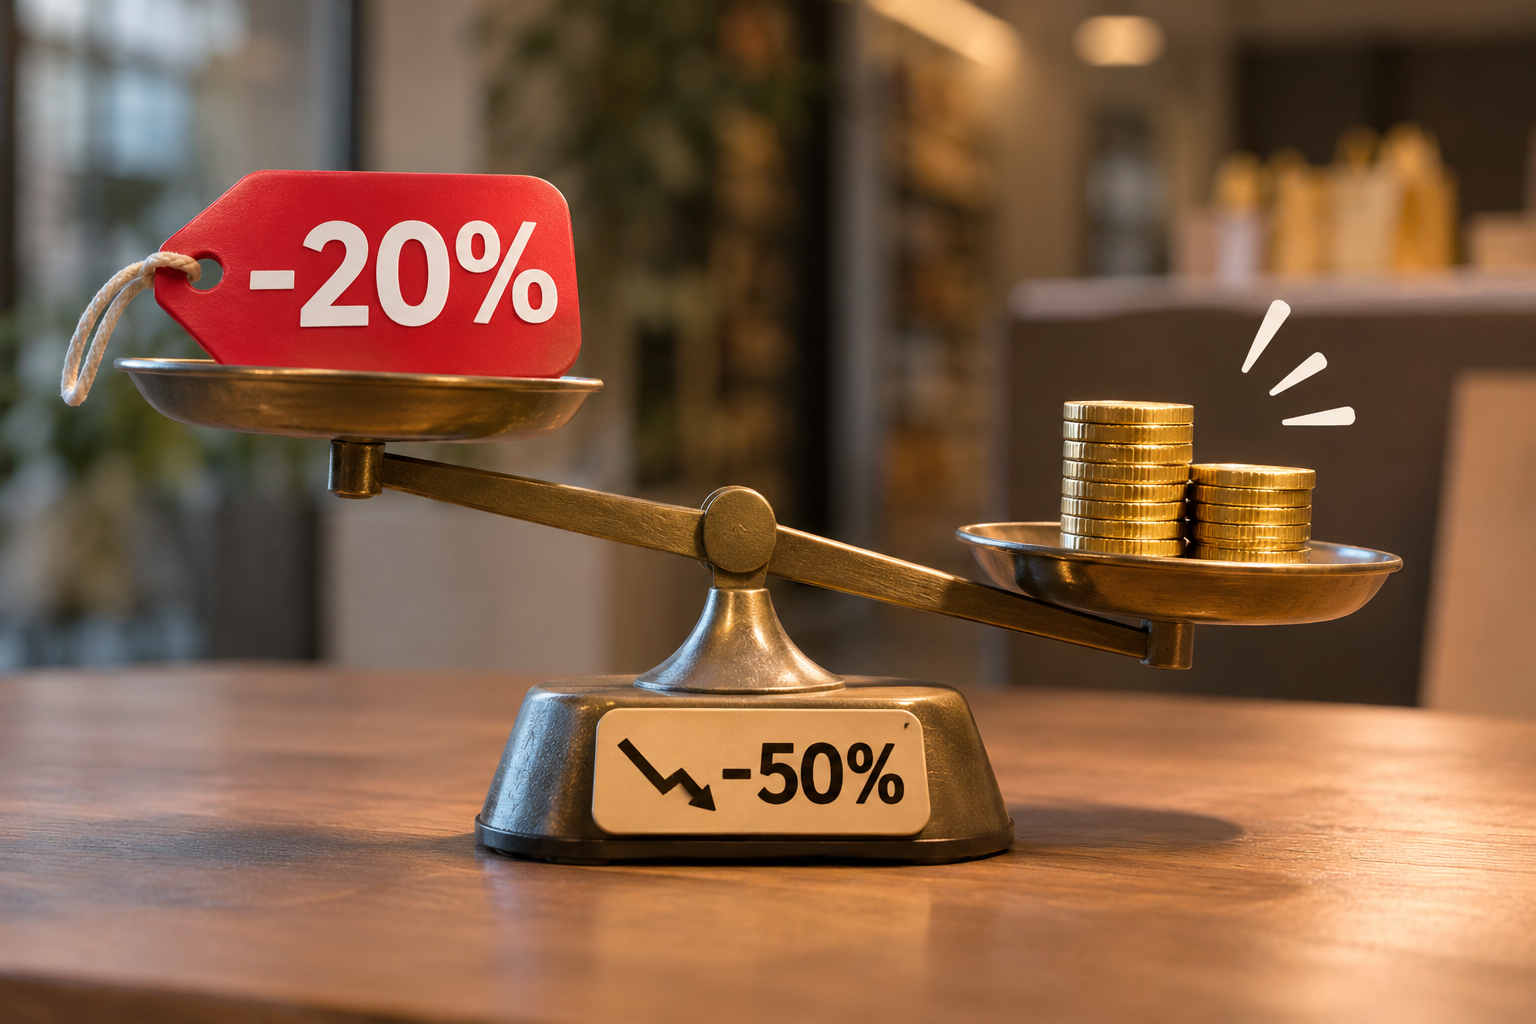
How Much Profit Do You Really Lose When You Offer a 20% Discount?
It was an ordinary working day in November. A store manager was looking through competitors’ posts. One promised deep discounts, another offered free delivery, and a third announced that the most anticipated sale of the year was about to begin. The marketing specialist had already prepared the store’s own offer: an attractive image, large numbers, and a simple promise: “20% off everything.” “Let’s launch it and get sales moving,” the manager said. “Twenty percent isn’t that much. We’ll earn a little less on each item, but we’ll sell more.”
The accountant asked him to hold the post for a few minutes. The accountant opened the figures for one of the products and asked:
“Do you know how much will be left from each sale after this discount?” The manager smiled. The answer seemed to be right there in the question. Twenty percent less. But the numbers on the page told a very different story.
When a fifth of the price takes away half the profit
Imagine a product that sells for AMD 10,000 and costs AMD 6,000 to purchase. To keep the calculation simple, let’s compare all amounts on the same basis, leaving VAT out of the example. We will return to delivery, advertising, and other expenses shortly. At the regular selling price, the difference is AMD 4,000. This is the gross profit on the product, from which the company still needs to cover its other expenses. The entire AMD 4,000 is not net profit that the owner can take home.
Now reduce the price of the same product by 20%. The customer pays AMD 8,000. The purchase cost remains AMD 6,000. Instead of AMD 4,000, just AMD 2,000 is left. The selling price has fallen by 20%, while gross profit per unit has fallen by 50%. The manager looked at the calculation again. What he had considered a small concession had actually taken away half the gross profit from that sale. The rent would not fall as a result. Neither would employees’ salaries.
But won’t we sell more?
That is a reasonable objection. A discount can attract new customers and bring in more orders. The question is how much sales need to grow to maintain the previous result. Suppose the store normally sells 100 units of this product. Each generates AMD 4,000 in gross profit, giving a total of AMD 400,000. After the discount, each unit generates AMD 2,000. To reach the same AMD 400,000, the store now needs to sell 200 units.
In this example, the number of units sold needs to double. That also assumes the purchase cost per unit stays the same and the extra sales do not create additional expenses. If you sell 150 units, the number of orders will rise by 50%, but gross profit will total AMD 300,000. The team will work harder, more stock will leave the warehouse, and you will still earn less than the previous AMD 400,000.
This is why judging a promotion’s success solely by order numbers can be misleading. The phone rings more often, couriers are busy, and the sales team is pleased. The financial result, however, only becomes clear later.
The same discount affects different products differently
Another common mistake follows: once the loss has been calculated for one product, the picture must be clear for the whole range. In reality, the same 20% discount may be acceptable for one product and completely eliminate gross profit on another. If a product sells for AMD 10,000 and costs AMD 8,000 to purchase, its original gross profit is AMD 2,000. After the discount, its selling price is also AMD 8,000. The purchase cost is covered, but nothing remains for other expenses.
If the purchase cost is AMD 7,000, just AMD 1,000 remains instead of the previous AMD 3,000. Gross profit falls by approximately 66.7%. So the phrase “20% discount” alone does not tell you how much profit you will lose. You need to know how much was left from each sale to begin with.
Expenses are part of the promotion too
A few days after launching the promotion, the manager noticed that orders had increased. But advertising costs had also risen. Some orders were being delivered at the company’s expense, and one employee was staying late to finish packing. None of this had been included in the initial calculation. It contained only the selling price and the product’s purchase cost. In practice, every additional order may come with a payment processing fee, packaging costs, delivery expenses, and a possibility of being returned.
Well-organised accounting helps reveal the full picture. If another AMD 700 of the AMD 2,000 remaining after the discount goes towards fulfilling the order, just AMD 1,300 remains to cover other expenses. At the end of the month, the owner may be surprised: sales have grown, but the expected result has not materialised.
A discount needs a clear purpose
This does not mean that offering a discount is a bad decision. Sometimes a company wants to sell end-of-season products, free up warehouse space, or recover cash that has been tied up in inventory for a long time. In that situation, earning the same profit on each unit may not be the main objective. In another case, a discount creates an opportunity for a first transaction with a new customer. Even then, it is worth asking whether that customer will return at the regular price or only buy during the next sale. Future sales need to move from an optimistic assumption to a measurable result.
That is why an experienced accountant may suggest selecting particular products rather than discounting the entire range, limiting the promotion’s duration, or testing the offer on a smaller scale first. Sometimes a product bundle or delivery on orders above a certain value is more profitable. Each option needs its own calculation.
Before publishing that big red number
The manager did not cancel the promotion that day. He simply asked for the offer to be revised. The team selected products that left enough money after the discount, calculated the additional expenses, and agreed to assess the results by profit as well. The marketing post went live a little later. But the team now understood why it was offering the discount and what result it expected.
Before your next promotion, it is worth having the same short conversation. Ask your accountant to show you three figures: how much remains from each sale now, how much will remain after the discount, and how much more you need to sell to make up the difference. Those figures are often more useful than your competitors’ most appealing advertisements.
The real cost of a 20% discount is reflected in the amount the company keeps after the sale. It is better to calculate that amount before the first discounted sale takes place.