What Happens If Your Accountant Does Not Come to Work Tomorrow
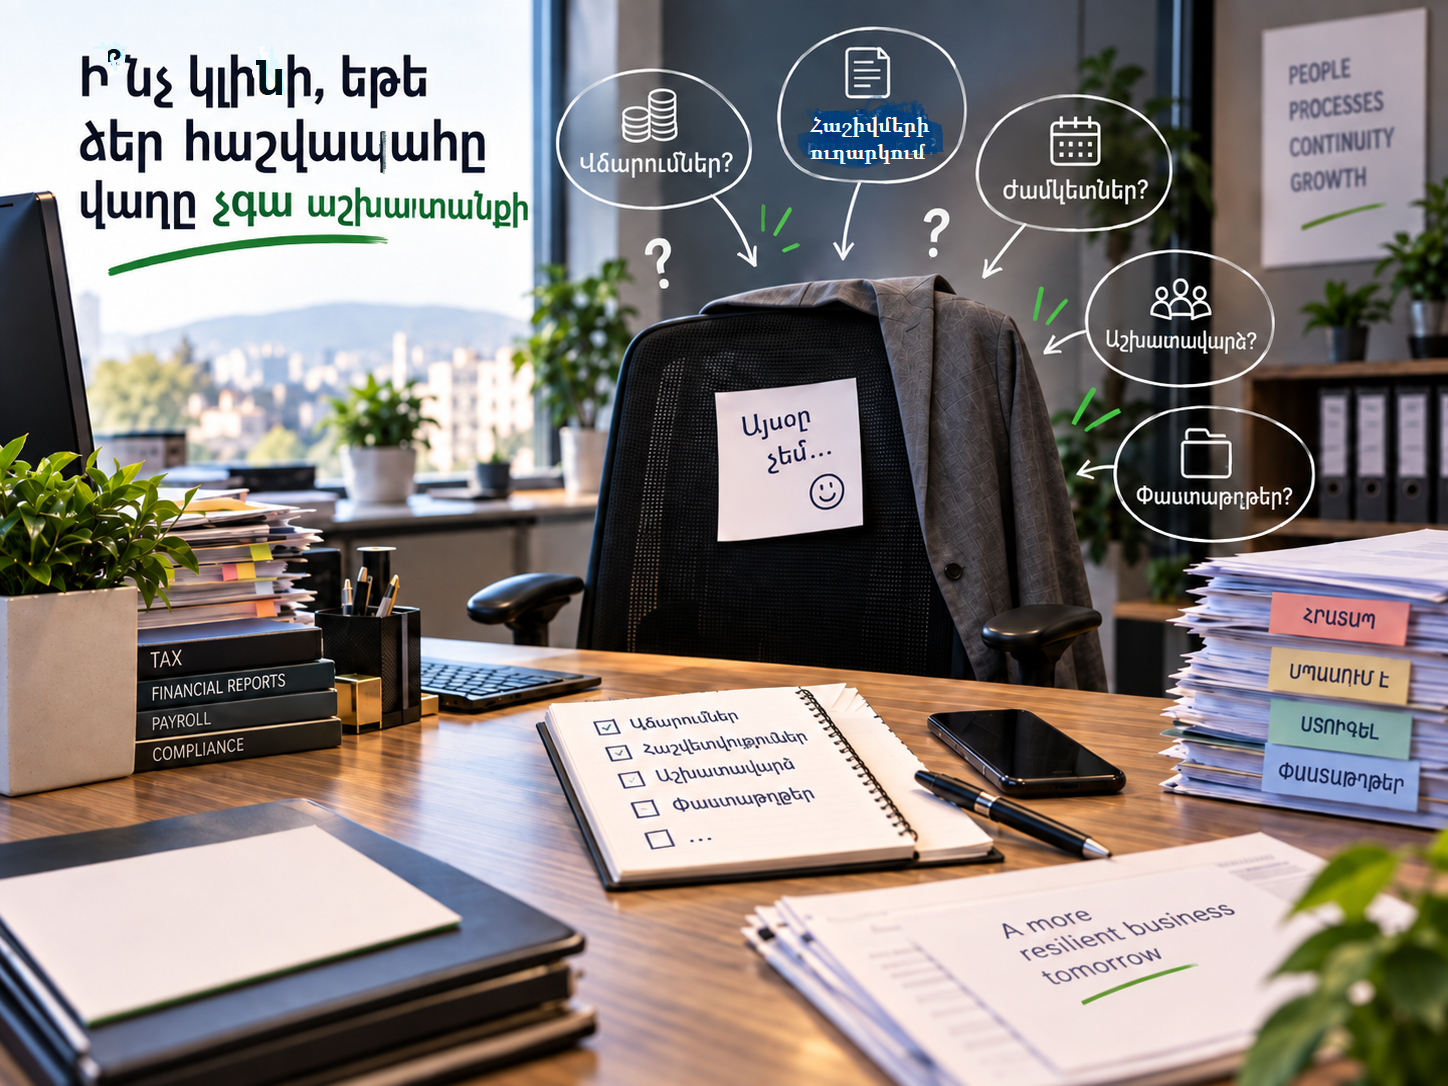
It is Monday morning. The company director is preparing to make an important payment, the sales department is waiting for an invoice under a new contract, and an employee is asking about holiday pay. The accountant normally handles all these matters. Today, however, the accountant’s phone is switched off. A few hours later, the company learns that the accountant is ill and will be unable to work for at least a week. At first, this seems like an ordinary workplace situation. Within a few hours, however, the director realizes that the problem is not merely one employee’s absence. The company’s entire accounting function depends on one person. Documents, tasks, passwords, and working arrangements are available only to that person.
When All the Information Is in One Person’s Head
In many companies, an accountant gradually becomes more than a specialist. The accountant becomes the memory of the entire system: who normally sends acceptance certificates late, which supplier balance remains unreconciled, which employee should receive an additional payment, and which transaction is subject to a verbal arrangement with the director.
As long as the accountant is available, this model seems convenient. If a question arises, someone calls. If a document cannot be found, everyone turns to the same person again. Yet this convenience is deceptive. When processes are undocumented, tasks are not monitored in one shared system, and records are scattered across computers and email accounts, the company does not have organized accounting. It has a dependency on one individual. Even the most responsible accountant cannot guarantee constant availability. The person may take leave, resign, or simply be unable to complete every task on time. If no one else can quickly understand the current state of work, a single day of absence becomes a management problem.
Payments Are the First Test
The first panic usually concerns bank transactions. Who knows which payments are urgent, which invoices have been approved, what purpose should be stated in a transfer, and whether enough cash has been reserved for taxes and salaries? If the entire payment process - from receiving the supporting document to approving the transaction in the bank - rests with one person, the company may delay a supplier payment or, conversely, transfer money without adequate support.
In a well-organized accounting system, the approval procedure is also clear to a backup employee or manager. Everyone should know who initiates a payment, who checks the contract and invoice, who approves the amount, and where the final document is stored. This is not needless bureaucracy. It is a mechanism that protects both the company’s resources and the accountant from unjustified responsibility.
Deadlines Come Next
Some accounting matters can be postponed for a day or two; other deadlines will not wait. Tax calculations, employee registrations, invoices, banking obligations, and documents to be provided to customers all have their own timing. If those deadlines exist only in the accountant’s personal calendar or memory, the company is not genuinely controlling its obligations.
The director does not need to open the tax calendar or check every filing each day. The director does, however, need confidence that every important deadline is recorded in a shared system, assigned to a responsible person, and given a visible status. The accountant’s absence then does not remove control. Another specialist can see what has been completed, what is waiting for a document, and what requires a management decision.
Where Are the Documents and Access Credentials
At a critical moment, the company may discover that the final version of a contract is in one person’s email account, a bank statement is on a computer desktop, and the credentials for the tax system are written on a piece of paper. When information is scattered, a backup specialist cannot simply continue the work. The specialist must first reconstruct the history of what has already been done.
A company needs a consistent document-storage policy. Contracts, invoices, acceptance certificates, and filing confirmations should be classified so that an authorized person can find them quickly. Usernames and passwords require a secure access procedure with clearly defined permissions and a process for temporary replacement.
Having a Backup Person Is Not Enough
Some directors believe the risk is covered because another accountant can help if necessary. A backup will be effective, however, only when that person already understands the company’s activities, software, tax regime, principal business partners, and current issues. A specialist who knows nothing about the company cannot safely take over years of accumulated accounting work within a few hours.
Backup capacity must be created before an emergency occurs. Processes should be documented, important transactions explained, and the status of current work updated regularly. It is useful to test the system from time to time with one simple question: if the main accountant is unavailable for three days, can someone else complete urgent work without guessing? If the answer is no, the company already has a risk, even when everything appears calm today.
What the Director Should Know
A director does not need to become an accountant, but must have basic visibility. The director should know which reports and returns are filed, when taxes are paid, who can access the bank and tax systems, where documents are stored, which issues remain unresolved, and who can replace the main specialist.
A short monthly meeting is often enough to preserve this visibility. The accountant can present expected taxes, accounts receivable and payable, missing documents, unusual transactions, and the next month’s important deadlines. Such a meeting reflects control, not distrust. It helps the company identify problems in time and prevents critical information from remaining with only one person.
The Advantage of Team-Based Accounting
The value of a team approach becomes particularly clear here. When a company is supported not by one accountant but by a coordinated group of specialists, duties and information are distributed. One person may handle daily transactions, another may oversee tax matters, and a third may review payroll and personnel records. The team discusses complex or unusual cases, while important deadlines receive a second level of control.
This does not mean that errors become impossible. It does mean that the system reduces the risk of the entire accounting function stopping because one person is absent. The client continues to receive answers, payments and filings are not overlooked, and a new specialist does not have to begin with a blank page. The completed actions, documents, and next steps are already visible.
An Accountant’s Absence Should Not Stop the Business
A good accountant is highly valuable to a company. Yet the work of even the most dependable specialist should be organized so that a temporary absence does not put the business at risk. Real protection does not come from hoping that the accountant will always be available. It comes from organized accounting: consistent document storage, controlled deadlines, secure access rules, and a prepared backup.
It is therefore worth asking a simple question today: if our accountant does not come to work tomorrow, will we continue operating normally, or will we spend the day searching for passwords, documents, and unfinished tasks? The answer describes the quality of an accounting system far more accurately than one return filed on time. Reliable accounting is not only about correct figures. It is also about uninterrupted work, regardless of who happens to be sitting at the computer at that moment.